

If you or a family member suffered a spinal cord injury caused by someone else in Nevada, Washington, or California, a spinal cord injury lawyer at Van Law Firm can establish who is responsible and pursue the lifetime cost of care.
We represent injured people in Las Vegas, Henderson, and Summerlin, across Washington from our Lakewood office including Seattle and Tacoma, and in California from Monterey Park.
- Cases we handle: vehicle and motorcycle collisions, falls from height and on unsafe property, construction and workplace incidents, diving and recreational injuries, and some defective products,.
- What we pursue: acute and rehabilitative care, assistive equipment, home and vehicle modifications, attendant care, lost earning capacity, and the loss of independence itself.
- Fees: Our personal injury law firm never charges upfront fees. We handle your case on a contingency, which means you don’t pay unless we win.
- Where we work: offices in Las Vegas, Nevada, Lakewood, Washington, and Monterey Park, California.
Complete and Incomplete Spinal Cord Injuries
Spinal cord injuries are described in two ways: by where on the cord the damage occurred, and by how much function was lost. The National Institute of Neurological Disorders and Stroke classifies injuries by spinal level, such as paraplegia or tetraplegia, and by severity, from mild and incomplete through to complete. The primary deficits are loss of sensation, loss of motor control, and loss of autonomic regulation.
- Complete injury. No sensory or motor function is preserved below the level of the injury, including in the lowest sacral segments.
- Incomplete injury. Some function remains below the level of injury. It may be sensation only, or sensation with partial motor control.
- Tetraplegia. Injury in the neck region, affecting the arms, hands, trunk, and legs. Formerly called quadriplegia.
- Paraplegia. Injury lower down, affecting the trunk and legs while arm and hand function is preserved.
Clinicians grade severity using the ASIA Impairment Scale, running from grade A for a complete injury through to grade E for normal function. That grade appears throughout the medical records and is one of the first things an insurer’s medical reviewer will look for.
Why the early classification is not the final one
A grade assigned in the first days after an injury is not a prognosis. Some people classified as complete convert to incomplete over the following year, and function can continue changing well beyond that. The reverse also happens, with secondary complications reducing function that was present early on.
This matters legally more than it might seem. An insurer that offers a settlement in the first months is valuing the case on an unstable picture, and once a release is signed there is no route back if the outcome turns out worse.
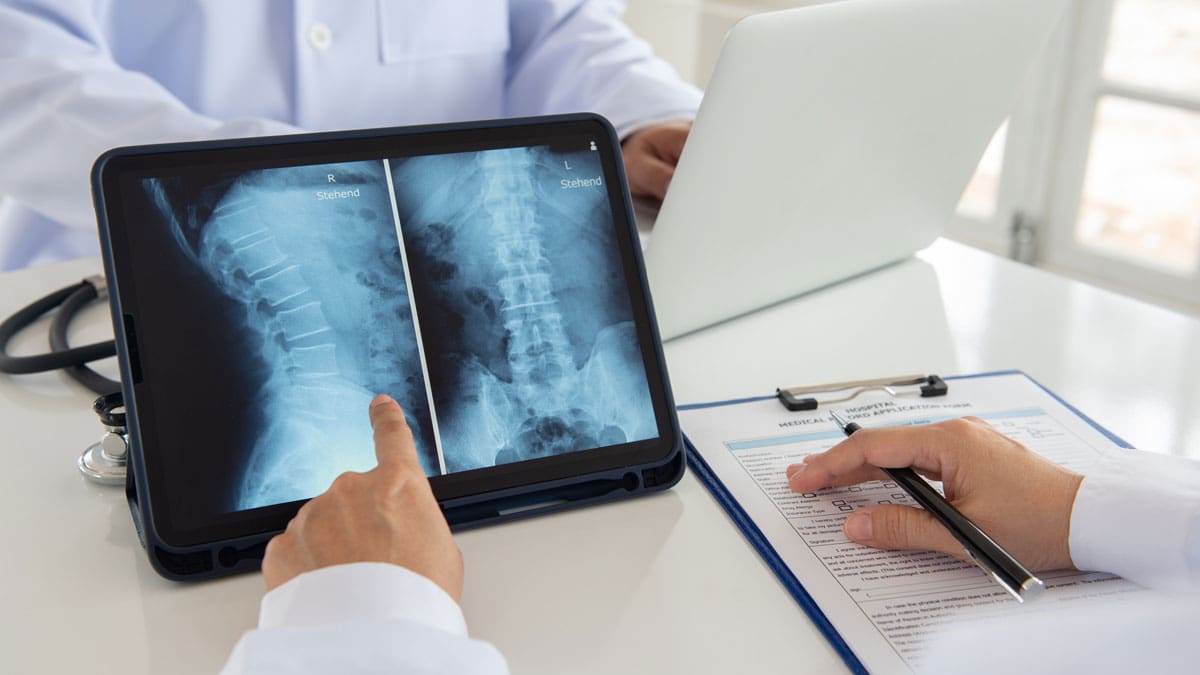
Common Causes
- Vehicle and motorcycle collisions. The leading cause, including rear-end and rollover crashes and collisions involving commercial vehicles.
- Falls. From height on construction sites, and on unsafe property from missing handrails, poor lighting, unmarked level changes, and unguarded edges.
- Workplace and construction incidents. Struck-by injuries, scaffold and ladder failures, trench collapses, and equipment failures.
- Diving and recreational injuries. Including pool and open-water incidents where depth was misrepresented or unmarked.
- Defective products. Seat and restraint failures, roof crush, helmet failures, and equipment that collapsed under normal use.
Paralysis and Long-Term Medical Consequences
Paralysis is the visible part. Much of the lifetime cost comes from the secondary conditions that follow it, and those are the categories insurers most often leave out of an early offer.
- Pressure injuries. A recurring and serious risk requiring specialist surfaces, repositioning, and sometimes surgical repair.
- Bladder and bowel dysfunction. Ongoing management, supplies, and a raised risk of urinary tract and kidney complications.
- Respiratory complications. Particularly with higher cervical injuries, where ventilatory support or assisted coughing may be needed.
- Autonomic dysreflexia. A medical emergency associated with higher-level injuries, requiring trained caregivers who recognize it.
- Spasticity and chronic pain. Including neuropathic pain that is often resistant to standard treatment.
- Cardiovascular, bone density, and mental health effects. Which accumulate over decades and shape both cost and life expectancy.
Who May Be Liable
Because the lifetime cost is so high, identifying every responsible party and every applicable policy matters more here than in almost any other claim.
- Drivers and their employers. Where a crash occurred during work, a commercial policy usually sits behind the driver’s own.
- Property owners and occupiers. For falls and diving injuries, where a hazard was known or should have been.
- Contractors and site controllers. On construction sites, general contractors and subcontractors alongside equipment suppliers.
- Product manufacturers. Washington sets out manufacturer liability by statute in RCW 7.72.030, while Nevada and California reach the same result through court decisions.
- Third parties in workplaces. Where the injury happened at work, a third-party claim against someone outside your employer can proceed alongside workers’ compensation and covers what it does not, including pain and loss of enjoyment of life.
- Government bodies. For dangerous road design, defective public property, or public transit incidents. These may carry much shorter notice deadlines.
Life Care Plans and Future Economic Losses
A life care plan is the document that makes a paralysis claim provable. Without one, future needs are an argument. With one, they are an itemized schedule with costs attached.
A certified life care planner reviews the medical records, consults the treating physicians, and builds a year-by-year projection of everything the injury will require for the rest of the person’s life. A forensic economist then converts that schedule into a present-day figure, accounting for inflation in medical costs and for life expectancy.
What a life care plan typically covers
- Physician, specialist, and rehabilitation visits at their expected frequency
- Attendant and personal care, including hours per day and skill level required
- Wheelchairs and seating systems, with replacement cycles rather than a single purchase
- Catheters, wound care, and other consumable supplies, costed annually
- Home modifications: ramps, doorway widening, accessible bathrooms, lifts, and flooring
- Vehicle modification or an accessible vehicle, with a replacement schedule
- Medication, for spasticity, neuropathic pain, and bladder management, and other symptoms
- Anticipated surgeries and hospitalizations for predictable complications
- Therapy: physical, occupational, and psychological
- Case management and caregiver training
Alongside the care plan sits the loss of earning capacity: not simply the wages missed so far, but the difference between the working life the person would have had and what remains available to them.
Non-Economic Damages and Loss of Independence
The categories without a receipt attached are substantial in these cases and should not be treated as an afterthought to the care plan.
- Loss of independence. Needing assistance with tasks previously done without thought is a distinct harm from the physical injury itself.
- Physical pain. Including chronic neuropathic pain that persists indefinitely.
- Psychological harm. Depression and anxiety are common after catastrophic injury and are compensable when documented.
- Loss of enjoyment of life. Activities, work, and relationships that are no longer accessible.
- Effects on the family. A spouse or domestic partner may have a claim for loss of consortium in all three states, and family members frequently take on caregiving that has a measurable value.
What any individual claim is worth depends entirely on its facts, the level and completeness of the injury, and the care required, so no one can responsibly quote a figure before the life care plan is built.
Evidence and Medical Experts
Catastrophic claims are contested harder than any other kind, because the amounts involved justify the defense spending heavily. The response is to build the case with the same rigor.
- Treating physicians and surgeons: establish the diagnosis, the level and completeness of the injury, and the prognosis.
- Physiatrist: a rehabilitation specialist who explains functional capacity and what recovery is realistically possible.
- Life care planner: builds the lifetime schedule of needs and costs.
- Vocational expert: assesses what work remains possible given the functional limits.
- Forensic economist: converts future care and lost earning capacity into present value.
- Accident reconstruction or safety engineer: establishes how the incident happened and whether a product, structure, or system failed.
Records and materials that help
You do not need any of this to start a conversation. Bring what you have and we help gather the rest.
- Ambulance, trauma center, and surgical records from the day of the injury
- Imaging and operative reports, and any ASIA classification recorded
- Rehabilitation and therapy notes, including functional assessments
- Equipment prescriptions, quotes, and receipts
- Photographs and video of the scene, the vehicle, or the hazard
- Employment records, tax returns, and evidence of career trajectory before the injury
- A record of who is providing care at home and how many hours it takes
- Any correspondence from insurers, including your own
What to Avoid
- Settling before the picture stabilizes. A release is permanent, and future deterioration cannot be reopened.
- Accepting a policy-limits offer without checking for other coverage. An early offer of a small policy limit often signals that the insurer expects a much larger claim and wants it closed cheaply.
- Giving a recorded statement during acute care. Function assessed in the first weeks may bear little relation to the eventual outcome.
- Assuming workers’ compensation is the whole claim. If the injury happened at work, a separate claim against a third party may exist and can cover losses that workers’ compensation does not.
- Posting rehabilitation milestones publicly. Video of a good day in therapy gets used to argue the limitations are overstated.
How We Develop a Catastrophic Injury Case
- Free consultation. We review what happened, the injury level, and the treatment underway. No obligation to proceed.
- Preservation and reconstruction. Letters go out immediately for footage, vehicle data, site records, and equipment, and where necessary an engineer examines the scene before it changes.
- Full coverage search. Every policy behind every potentially responsible party, because the lifetime cost commonly exceeds a single limit.
- Medical development. We work with the treating team until the prognosis is stable, then commission the life care plan and economic analysis.
- Demand and negotiation. Once the medical picture is clear, a demand is sent and negotiation may follow to resolve the claim.
- Nevada claims are commonly filed in the Eighth Judicial District Court in Clark County, and many Washington claims in Pierce County Superior Court. California claims from the Monterey Park area are commonly filed in Los Angeles County Superior Court.
- Most claims settle without a trial. Where a settlement is structured over time, we address how future medical funding and any liens are handled before anything is signed.
Deadlines to File a Spinal Cord Injury Claim
Nevada
- Most claims: two years from the date of injury under NRS 11.190(4)(e).
- Injured children: NRS 11.250 pauses the clock until the injured person turns 18.
Washington
- Most claims: three years from the date of injury under RCW 4.16.080(2).
- Injured children: RCW 4.16.190 tolls the period while the injured person is under 18.
- Claims against the state: RCW 4.92.100 requires a claim to be filed and a 60-day waiting period before suit.
California
- Most claims: two years from the date of injury under Code of Civil Procedure section 335.1.
- Injured children: section 352 tolls the period until the injured person turns 18.
- Claims against a public entity: a government claim must generally be presented within six months under Government Code section 911.2.
Frequently Asked Questions
What is the difference between a complete and incomplete spinal cord injury?
A complete injury leaves no sensory or motor function below the level of the damage, including the lowest sacral segments. An incomplete injury preserves some function, which may be sensation alone or sensation with partial movement. Clinicians grade this on the ASIA Impairment Scale from A to E, and the grade appears throughout the medical records.
Who can be held liable for a spinal cord injury?
Whoever’s carelessness caused it, and can be more than one party. That may include a driver and their employer, a property owner who left a hazard unaddressed, a contractor on a worksite, a product manufacturer, a healthcare provider, or a government body responsible for a dangerous road. Identifying all of them matters because each carries separate insurance.
What is a life-care plan and why is it important?
It is a year-by-year projection of everything the injury will require for the rest of your life, built by a certified planner from the medical records and the treating physicians’ input. It covers care hours, equipment and its replacement, supplies, surgeries, therapy, and home and vehicle modifications. Without one, future needs are argument rather than evidence.
Can compensation include home modifications and assistive equipment?
Yes, and these are components of a life care plan. Ramps, doorway widening, accessible bathrooms, lifts, and flooring may be recoverable, as are wheelchairs and seating systems. Equipment is costed on replacement cycles rather than as a one-time purchase, because a wheelchair bought today will need replacing many times over a lifetime.
Which medical and economic experts may be required?
Typically a treating surgeon and a physiatrist to establish the injury and prognosis, a life care planner to build the schedule of future needs, a vocational expert to assess remaining work capacity, and a forensic economist to convert those figures to present value. An accident reconstruction or safety engineer is often needed to establish how the incident happened.
What if the injury worsens after settlement?
Generally there is no remedy, which is why timing matters so much. A settlement release is permanent and closes the claim regardless of what happens afterwards. Since secondary complications such as pressure injuries and respiratory problems can develop years later, a life care plan should account for them before anything is signed.
How long do I have to file a spinal cord injury claim?
Two years in Nevada under NRS 11.190(4)(e), three years in Washington under RCW 4.16.080(2), and two years in California under Code of Civil Procedure section 335.1. Claims involving medical negligence or a government body run on different and often much shorter deadlines.
Client Testimonials
Related Videos